Growth Has Stalled. The Factory Still Opens Monday.
What an Area Sales Manager can actually do when the business stops growing. Operational field tactics for routes, store availability, shelf capacity, and trade spend.
Growth Has Stalled. The Factory Still Opens Monday.
What an Area Sales Manager Can Actually Do When the Business Stops Growing
There is a particular kind of discomfort that settles over an FMCG sales meeting when growth has gone flat. Nobody is in panic mode yet, which somehow makes the atmosphere worse. The business is still profitable, the factory is still producing, the distributor is still ordering and the sales team is still out in the market every day, but the numbers have stopped moving in the direction everyone prefers. At corporate level, the conversation quickly becomes strategic. Someone suggests innovation, someone else mentions adjacent categories, Strategy begins talking about acquisitions and Finance quietly asks what any of this is going to cost.
All of those ideas may be perfectly sensible, but they are usually far removed from the reality of the Area Sales Manager sitting in Semarang, Surabaya or Bekasi on Monday morning. He cannot acquire a company because the area is behind target, he cannot launch a new category by Wednesday and he cannot ask R&D to produce a miracle product because sell-out has been soft for three months. He has to work with the same brands, the same SKUs, the same distributor, the same salespeople, the same outlets and roughly the same trade budget he had last week. That is where stagnant growth becomes operational, because the challenge is no longer “what should the company do?” but “what can I change in my area with the resources already in front of me?”
At field level, stagnant growth is almost never one large problem. It is usually a collection of smaller commercial failures that have accumulated quietly over time. The best-selling SKU is repeatedly out of stock in the strongest outlets, the route plan still reflects a territory that existed three years ago, the distributor has too much inventory of slow-moving SKUs and too little of the products that actually sell, and trade money is being spread across accounts because it always has been rather than because those accounts deserve it. None of these issues sounds dramatic enough to justify a board presentation, but together they can explain why an area that once grew comfortably has suddenly become stubborn.
This is the first useful mindset shift for an Area Sales Manager. Instead of asking, “How do I create another eight percent growth?” it is much more productive to ask, “Where am I already losing sales that I should be winning?” The first question is broad, strategic and intimidating; the second can be taken into the field on Tuesday morning. It turns growth from an abstract number into a series of physical situations involving routes, stores, stock, salespeople, shelf space and competitors.
Imagine an area doing Rp120 billion in annual sales while growing at one percent in a category that is still growing at four. Head office sees the three-point gap and asks for a recovery plan, which is understandable. The easiest response is to push harder: ask the distributor to load more stock, tell supervisors to increase calls, add another promotion and hope that month-end closes strongly enough to make the slide look respectable. That approach can work for a short period, but it often solves September by borrowing from October. The stock gets pushed into the channel, the month closes better, and a few weeks later the same team discovers that the market is full and the next target has become even harder.
A stronger Area Sales Manager starts by breaking the territory apart. He looks at which cities are weak, which channels are behind, which routes are deteriorating, which salespeople have poor strike rates, which SKUs are losing velocity and which accounts are repeatedly running out of stock. He looks at distribution quality rather than just outlet count, and he compares weighted distribution with actual market share to see whether the problem is access or performance. If most of the gap is concentrated in a handful of clusters, there is very little point in applying equal pressure across the entire area. The objective is not to produce another dashboard but to turn a vague growth problem into a small number of solvable commercial issues.
This is where averages can become dangerous. A territory may report respectable average sales per outlet, a healthy average strike rate and decent average stock cover, yet those averages can hide huge differences between customers. One store may sell ten times more than another, one route may have twice the productive call rate of another and one cluster may be carrying the area while another quietly loses share. The Area Sales Manager who manages the average is often managing a version of the market that does not actually exist.
The better approach is to rediscover the territory as a collection of very different commercial environments. A minimarket beside a commuter station behaves differently from one in a suburban housing cluster, and a warung near a university has a different shopper mission from an outlet near a factory gate. The same product may perform very differently across those environments, yet national execution plans tend to arrive in neat, standardised packages. That consistency makes planning easier, but it does not always make selling more effective. The area manager’s job is not to ignore the national plan but to interpret it intelligently in the local market.
If one cluster over-indexes heavily on immediate consumption, then cold availability, single-serve packs and rapid replenishment matter more there than the national average might suggest. If another cluster is family-oriented and performs better on larger take-home packs, the execution should reflect that. The difference between a good and average area manager is often not that one has access to better strategy, but that one notices these local differences and acts on them before they become obvious in the monthly report.
Distribution is another area where stagnant businesses often respond too broadly. “We need more distribution” sounds sensible because more doors should mean more sales, but not all doors are worth the same. If the brand is absent from high-value outlets where the category is strong, expanding distribution is a real growth lever. If the remaining white space consists mostly of small, low-velocity stores, chasing additional doors may improve numerical distribution while doing very little for revenue.
This is why outlet count can be one of the most comforting and misleading numbers in field sales. Tell a team to open 2,000 outlets and, given enough pressure, it will probably open 2,000 outlets. Sales organisations are very good at delivering the metric attached to the incentive. The more important question is whether those outlets represent enough category value to justify the time, stock, trade investment and call frequency they require.
Suppose the Area Sales Manager has two choices. The first is 1,500 relatively easy outlets that together account for only two percent of category value. The second is 180 more difficult stores that represent seven percent. The first option produces a much nicer outlet-count chart, while the second may produce a much nicer P&L. A strong manager understands that the job is not to maximise the number of doors but to maximise the number of valuable doors the business can win and service properly.
This is also where operational creativity begins to matter. The strongest outlets are usually difficult precisely because the competition knows they are strong too. You may not have the largest trade budget or the strongest national campaign, so the way in may be through something the competitor is doing badly. Perhaps service is weak, perhaps the retailer is unhappy with the case configuration, perhaps the competitor regularly runs out of stock, or perhaps the assortment is not suited to the shopper profile. Operational creativity is rarely magic. More often, it is paying attention to something the competitor has become too comfortable to notice.
Route planning is another source of hidden growth because routes tend to become institutional memory. Once a call plan exists, it acquires a strange authority. The salesperson visits Outlet A every Monday because Outlet A has always been visited every Monday, even though the area around it may have changed completely. New housing appears, traffic patterns shift, one account declines, another becomes a major wholesaler and new minimarkets open nearby, yet the route often continues as if the territory has been frozen in time.
This is where an Area Sales Supervisor can create real value. The route map should be compared with current sales, outlet potential, travel time, strike rate and order frequency. A salesperson may be spending forty minutes reaching a weak account that generates a tiny order while stronger stores nearby are under-serviced. Another account may be visited twice as often as necessary because the original call frequency was never reviewed. In a market like Indonesia, where traffic can consume a large part of the day, bad route design quietly destroys productivity even while the team looks extremely busy.
Busy teams are not automatically productive teams. A salesperson who visits thirty outlets and secures twelve orders may look harder-working than one who visits twenty-two and secures eighteen, but the second person may generate better sales, stronger average drop size and more effective execution while using less fuel. This is why call count should never be viewed in isolation. If strike rate is weak, the manager needs to understand whether the cause is selling skill, outlet selection, excessive call frequency, wrong assortment or even overstocking from the previous visit.
The field remains the best place to understand that difference. Ride with the strongest salesperson and then with the weakest. One may enter the store already knowing the previous order, current stock situation and the objective of the call, while the other asks a generic question about whether the retailer wants to order anything and accepts “no” as the end of the conversation. Both have technically made one call, but only one has really sold.
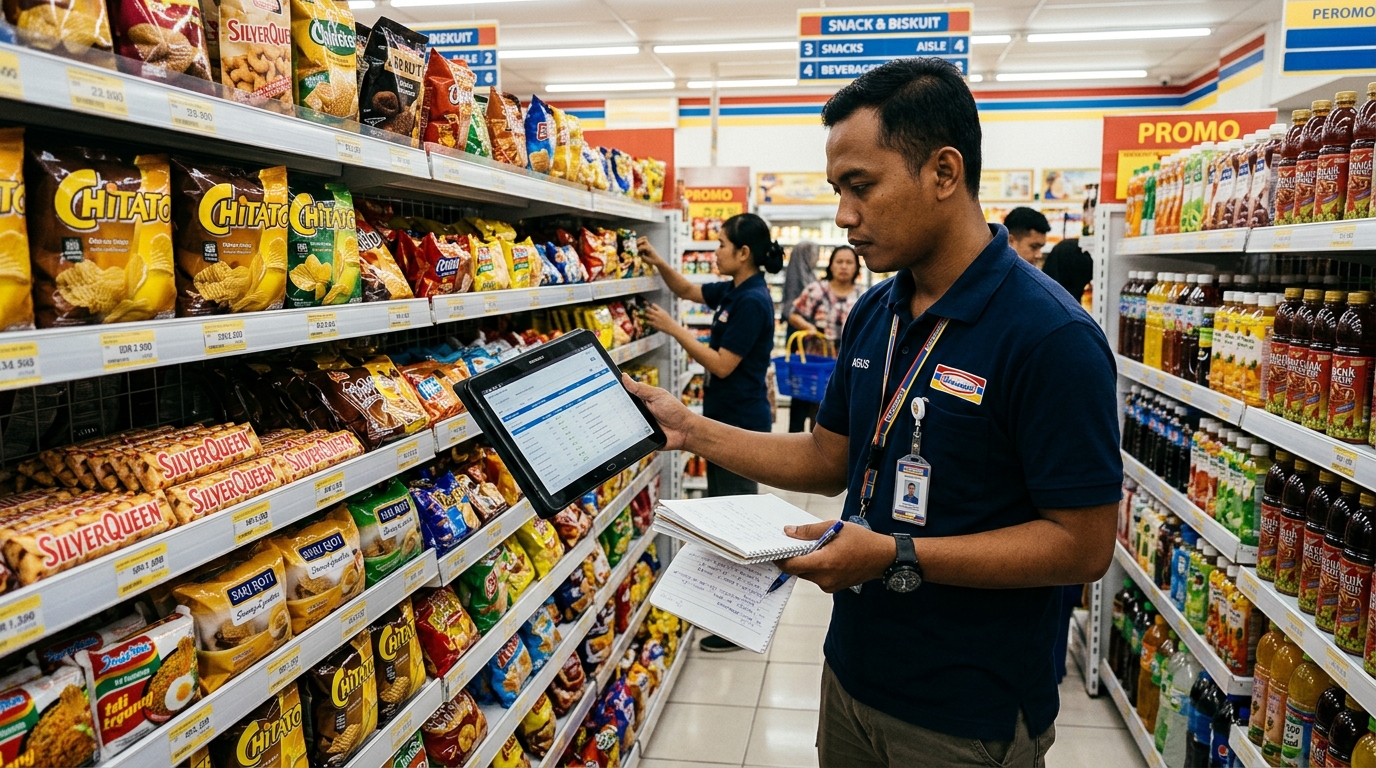
Availability is another obvious source of growth that often gets treated as somebody else’s responsibility. If the key SKU is repeatedly missing from the top stores, the area does not primarily have a marketing problem; it has an execution leak. The consumer has already been convinced, walked into the outlet and decided to buy. The organisation has simply failed to place the product in front of her at the right moment.
An Area Sales Manager should therefore know which SKUs matter most and where availability fails most often. National or regional averages can be misleading because a territory may report 94% availability overall while the top thirty stores repeatedly run out of the number-one SKU on weekends. The average looks healthy, but the sales opportunity is leaking exactly where it matters most. This is why a manager needs to look below the headline percentage and understand which outlets, which SKUs and which days are creating the problem.
Sometimes the fix is simple. The minimum stock level may be too low, the shelf may be too small, the distributor may replenish too slowly or store staff may not move stock from the back room quickly enough. In other cases the problem sits upstream, with the distributor holding enough total inventory but the wrong inventory mix. A warehouse can be full and the market can still be short of the product everyone wants. That particular combination manages to upset Sales, Supply Chain and Finance at the same time, which is quite an achievement.
For that reason, the distributor warehouse should be mentally inside the Area Sales Manager’s territory. He does not need to become a warehouse manager, but he does need to know whether the stock profile supports the field. Walking the warehouse can sometimes reveal more than another meeting. Slow flavours may be stacked to the ceiling while the core SKU has only a few days of cover, and the sales team may be complaining about shortages while Finance is looking at total stock and wondering what the problem is.
This is where the area manager acts as the bridge between field reality and supply reality. Head office sees reports, the distributor sees inventory and the salesman sees what retailers actually ask for. Growth depends on those three views being connected. Otherwise the business ends up in the absurd position of having too much stock overall and not enough of the one product that could actually generate sales.
Competitor intelligence is another area where field teams can become much sharper. Most sales organisations collect competitor information, but much of it ends up as a collection of photographs showing new displays, new prices and new packs. Those reports can be visually impressive and commercially useless. The important question is not merely what the competitor did, but where the competitor is weak enough to attack.
If a competitor repeatedly runs out of stock in the same stores every Saturday afternoon, that is not just information; it is an opportunity. If its field force visits certain high-value stores only once per week while your economics support a more frequent call, that can be exploited. If its promotional pack moves well in modern trade but poorly in traditional trade, the pattern may reveal a gap in execution. A smaller competitor may not have the budget to dominate nationally, but it can still win locally by moving faster where the market leader is slow.
Speed is one of the few advantages an area team can create without asking head office for more money. Large organisations often have more resources, but those resources come with meetings, approval chains and national consistency requirements. An Area Sales Manager who spots a local pattern on Tuesday may be able to act by Wednesday. If the competitor needs two weeks to discuss the same issue, the smaller local response has already had ten days in the market.
Trade spending deserves the same discipline. In stagnant territories, commercial investments often continue because they existed the previous year. A customer receives an allowance because it always has, a local display programme survives because nobody has formally killed it, and a promotional mechanic is repeated because removing it would require an uncomfortable conversation. Over time, trade spending can become less like strategy and more like archaeology.
The Area Sales Manager should know where the money actually works. If a certain display format consistently produces strong incremental sales in high-traffic outlets but does almost nothing in residential stores, it should not be deployed equally. If a 20% discount generates nearly the same volume uplift as 30%, the extra ten points are simply margin leaving the business in a very organised way. If a wholesaler incentive improves downstream distribution across hundreds of productive outlets, that may deserve more attention than several smaller activities that look good but do little.
This is how a smaller budget can outperform a larger one. The competitor may spend more in total, but the area team can still spend better by concentrating investment where it changes behaviour. Commercial resources do not need to be distributed fairly; they need to generate returns. That sounds obvious until every supervisor, channel and customer begins asking for an equal share.
Shelf productivity is another operational lever that often gets overlooked because shelf space is treated mainly as a visibility issue. It is also a capacity issue. If a fast-moving SKU sells twenty units a day and the shelf holds eight, the brand is structurally designed to go out of stock unless store replenishment is excellent. In that case, another facing is not just about looking bigger; it is about holding enough product to survive the selling day.
This creates a stronger retailer conversation because the sales team can argue from velocity rather than emotion. Asking for more space because the brand wants more space is weak. Showing that the current shelf capacity is causing repeated stock-outs in a high-volume SKU is a much better commercial case. Retailers understand productivity, and if one SKU sells ten times faster than another while receiving equal space, the planogram may be visually neat but economically poor.
The existing portfolio can often work harder too. When growth slows, everyone starts asking when the next launch is coming, even though the current range may not be fully optimised. Some SKUs drive volume, some drive margin, some are strategically important and some mainly create complexity. A slow-moving SKU consumes working capital, warehouse space, selling time and shelf capacity even if nobody has the courage to admit that it contributes very little.
The Area Sales Manager may not have authority to delete products, but he can still focus execution where it matters. If the 500ml pack generates more than half the area's sales, it should not receive the same attention as a flavour contributing three percent. If a small pack is critical in traditional trade because the opening price point matters, the field team should protect its availability. If a larger family pack performs best around payday in specific clusters, the call plan and stock positioning should reflect that. The products already exist; the opportunity is to deploy them more intelligently.
Coaching becomes even more important when the market stops doing the heavy lifting. In a rapidly growing category, weak execution can hide inside market momentum. A mediocre salesperson can look surprisingly competent when the category is growing 15%. Stagnation removes that protection, which is why the quality of supervision becomes much more visible.
A good Area Sales Supervisor should therefore spend less time asking whether the salesperson hit yesterday's number and more time understanding how the call was made. Did the rep prepare before entering the outlet, know the stock situation, sell the right assortment, ask for additional space and notice what the competitor was doing? Did he leave with a clear next action, or did he simply collect an order and move on? Those behaviours matter because they compound across hundreds of calls.
Field visits should be coaching, not inspection tours. The weakest version of supervision is a manager riding along, pointing out everything the salesperson did wrong and returning to the office feeling productive. The stronger version is identifying one or two behaviours that materially improve results and working on them repeatedly until they become habit. A salesperson who improves average drop size or strike rate permanently is worth far more than a temporary push that disappears when the incentive ends.
Routine is one of the biggest risks in mature territories because people stop asking questions. The salesperson knows the stores, the retailers know the salesperson and the route becomes comfortable. Calls become transactional rather than commercial. The rep asks for the order, checks a few products and leaves, while the competitor may be doing exactly the same thing one hour later.
The Area Sales Manager’s job is to make the team curious again. Why did this outlet suddenly grow? Why does the same pack perform much better five kilometres away? Why does one retailer reorder every four days while another similar store takes ten? Why has the competitor gained space in this cluster but not the next? These questions create operational intelligence, and in a market as varied as Indonesia the field team often sees the answers long before head office does.
The macro growth target only becomes useful when it is translated into these micro opportunities. Head office may ask for eight percent growth, but the Area Sales Manager should be able to show where that growth is expected to come from. Part may come from restoring availability in high-value stores, part from closing weighted-distribution gaps, part from improving route productivity, part from better trade-spend allocation and part from stronger shelf execution.
At that point, the target stops being one intimidating number and becomes a set of manageable commercial opportunities. A supervisor can work on a weak route, a salesperson can improve execution in specific stores, the distributor can correct stock mix and the area manager can concentrate resources on the parts of the territory that matter most. That is far more useful than telling the entire team to push harder and hoping enthusiasm somehow becomes revenue.
This is also where the Area Sales Manager can genuinely outsmart a larger competitor. He may not control the national media budget, innovation pipeline or acquisition strategy, but he does control where the team spends time, which outlets receive attention, how quickly local problems are fixed and how sharply the territory reacts to competitive weakness. Those decisions may look small individually, but FMCG is an accumulation business. One avoided stock-out, one better route, one extra facing, one improved order and one better use of trade money repeated across hundreds of outlets eventually becomes meaningful market share.
That is why operational turnarounds rarely come from one heroic intervention. They usually come from a collection of ordinary things being done noticeably better. The category may remain mature, the portfolio may remain unchanged and the company may still be waiting for the next major launch, yet the area can start growing again because less revenue leaks out through poor execution.
For the Area Sales Manager, that is the practical advantage of thinking this way. Growth does not have to arrive from somewhere above. It can be found in the territory, in the stores, in the routes, in the warehouse and in the behaviour of the team. The factory will still open on Monday, the distributor trucks will still leave the warehouse and retailers will still open their doors. Consumers will still buy something, and the operating challenge is simply to make sure that a little more of that something belongs to you rather than the competitor.
Tools for this topic
View shopFMCG Growth Systems (Hardcover)
A tactical leadership guide for building scalable FMCG growth engines.
Commercial Execution Tee
Soft cotton tee celebrating disciplined FMCG execution.
FMCG by Alex Notebook
Dot-grid strategy notebook for planning weekly commercial priorities.
Related content
Stop Riding Around With Your Salesman: How an Area Sales Supervisor Should Actually Spend a Day in the Field
A field visit only becomes valuable when something in the territory is actually better because the supervisor was there. Here is how FMCG area sales supervisors move from ceremonial ride-alongs to route quality, real coaching, and disciplined field execution.
The Product Is Everywhere. So Why Is It Always Out of Stock?
Why distribution, availability, and being able to actually buy the product are not the same thing. How out-of-stocks silently destroy FMCG sales while internal dashboards stay green.
The 30-Store Trap: Why FMCG Growth Comes From Developing Existing Outlets, Not Just Visiting More of Them
Visiting 30 outlets a day is easy to measure, but real FMCG growth happens inside the store. Here is how field salespeople move beyond basic replenishment, overcome 'Masih ada stok, Mas,' and expand from one SKU to eight in Indonesian general trade.
How to Build a Better FMCG Route-to-Market
Designing channel roles, distributor economics, and service levels in one RTM framework.